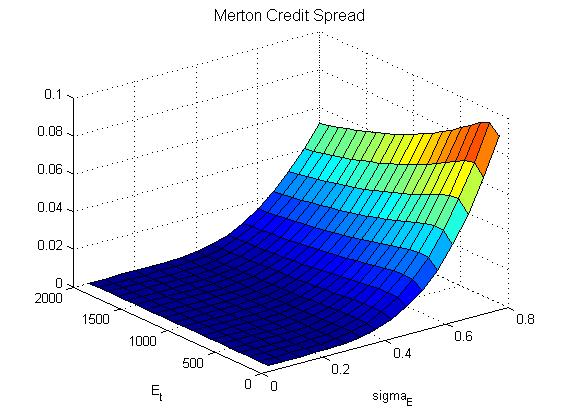
Merton Structural Credit Model (Matrixwise Solver)
Matrixwise Calculation Firm Asset Value, Volatility, Debt Value, Spread, Default Prob, Exp-Recovery

Al momento, stai seguendo questo contributo
- Vedrai gli aggiornamenti nel tuo feed del contenuto seguito
- Potresti ricevere delle email a seconda delle tue preferenze per le comunicazioni
Cita come
Mark Whirdy (2026). Merton Structural Credit Model (Matrixwise Solver) (https://it.mathworks.com/matlabcentral/fileexchange/39717-merton-structural-credit-model-matrixwise-solver), MATLAB Central File Exchange. Recuperato .
Riconoscimenti
Ispirato da: MTIMESX - Fast Matrix Multiply with Multi-Dimensional Support
Informazioni generali
- Versione (2,87 KB)
Compatibilità della release di MATLAB
- Compatibile con qualsiasi release
Compatibilità della piattaforma
- Windows
- macOS
- Linux
| Versione | Pubblicato | Note della release | Action |
|---|---|---|---|
| 1.5.0 | Removed fsolve dependency (Optim Toolbox) for efficiency increase (even in scalar inputs case) Full Code re-factorization to facilitate matrixwise calculation of bivariate ranges of {E_t,sig_E,K,T} values using 3d Newton Jacobian solution. |
||
| 1.4.0 | Added the Black-Scholes Parameter Anonymous Function Handle as an Output to allow for further analysis (sensitivity, greeks etc) d = @(z,A_t,sig_A,T,t,K,r)((1/(sig_A*sqrt(T-t)))*(log(A_t/K) + (r + (z)*0.5*sig_A^2)*(T-t))); z = +1/-1 |
||
| 1.3.0 | Minor code refactoring, code returns the Black-Scholes Parameter to allow for further sensitivity analysis & calculation of greeks d = @(z,A_t,sig_A,T,t,K,r)
|
||
| 1.1.0 | Added Expected-Recovery calclulation [A_t,sig_A,D_t,s,p,R] = calcMertonModel(E_t,sig_E,K,t,T,r); |
||
| 1.0.0 |

